For 2027, one of the most important Medicare Advantage changes may be happening behind the premium.
There’s an easy way to review a Medicare Advantage plan and a better way. The easy way is to look at the monthly premium.
The better way is to ask:
That question deserves extra attention for 2027. Major Medicare Advantage insurers are responding to higher healthcare utilization and pressure on plan profitability by reconsidering their geographic footprints and provider networks.
On October 1st, Reuters reported that UnitedHealthcare and Aetna are moving toward more limited provider networks in portions of their 2027 Medicare Advantage businesses. Aetna is emphasizing more HMO offerings, while UnitedHealthcare is reducing some exposure to PPO markets.
That matters because an HMO and PPO can provide very different levels of flexibility. PPO plans generally allow members to receive covered services outside the plan’s network, although costs may be higher. An HMO plan typically places considerably greater importance on staying within its network, except in certain circumstances such as emergencies.
Neither structure is automatically good or bad. But the difference becomes very important if you’ve spent years building relationships with particular physicians, specialists, or healthcare systems.
And this isn’t occurring because Medicare Advantage is disappearing. CMS says more than 99% of Medicare beneficiaries will have access to at least one Medicare Advantage plan in 2027, and 97% will have access to at least 10. The average Medicare Advantage premium is actually projected to fall to $12, though many plans are still $0.
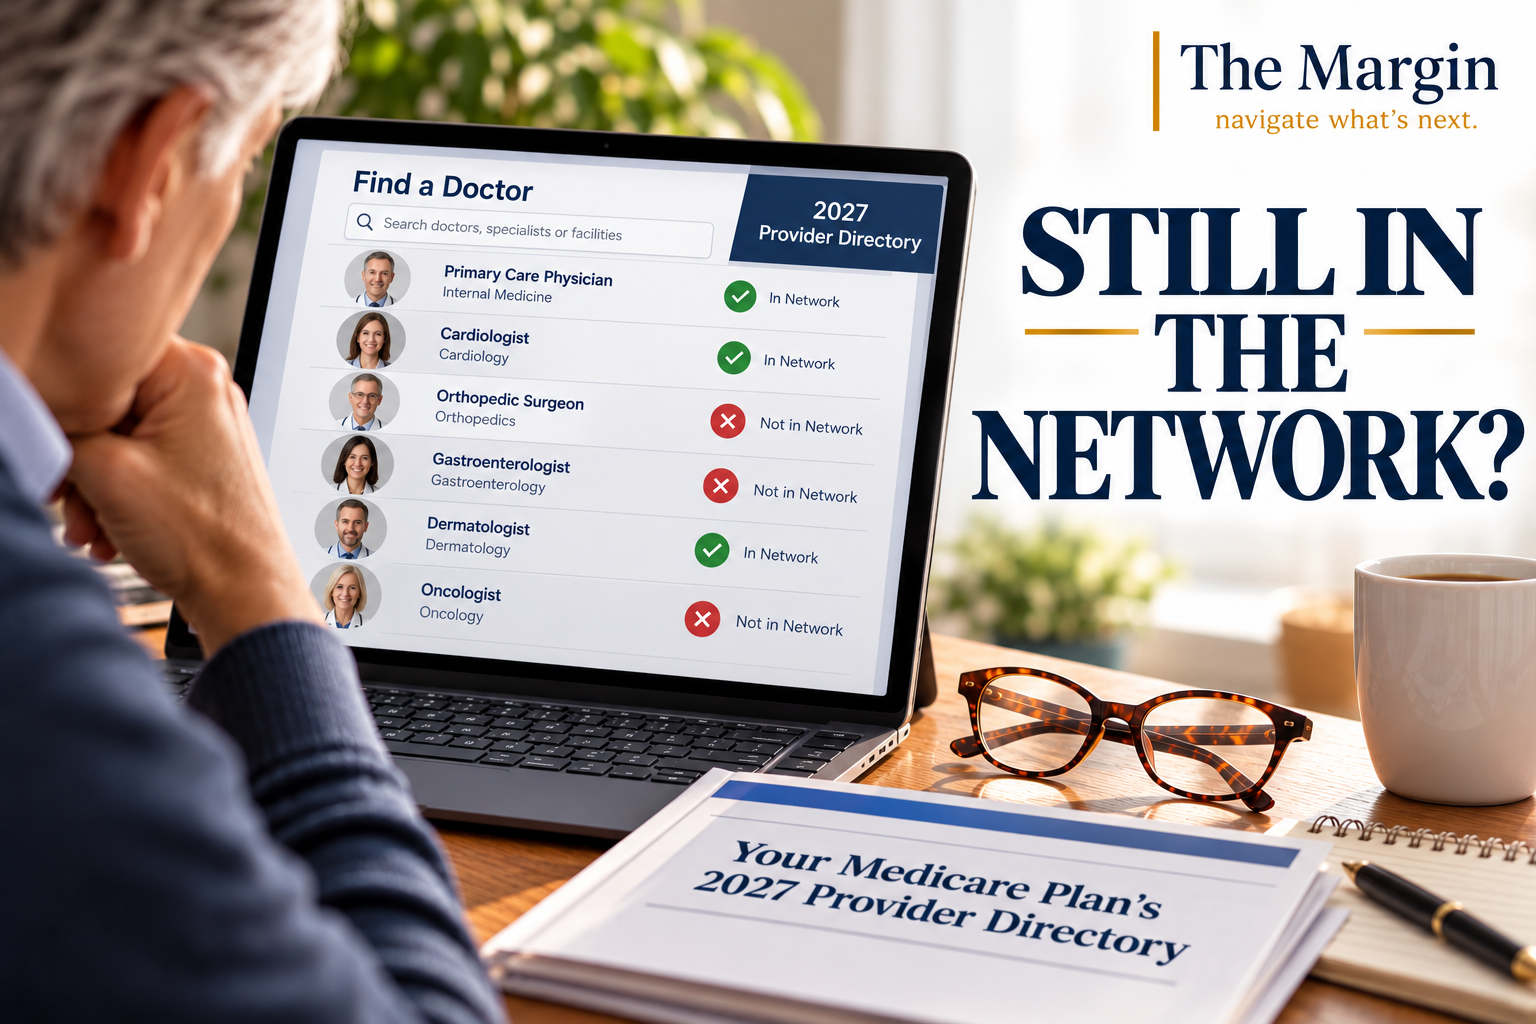
In some places, the choice within a plan may matter more than the price of the plan itself. For Medicare beneficiaries, I would put provider verification near the top of the AEP checklist this year. Don’t simply ask whether your insurance company is returning. Ask whether your specific plan is returning and if that plan is changing networks.
Then verify that your primary care physician, specialists, and preferred hospitals are in network. If you have an important procedure planned for 2027, I’d pay particular attention to the physicians and facilities involved. And don’t rely exclusively on what was true in 2026. Networks can and do change.
One final point: seeing a doctor’s name in an online directory is useful, but for physicians who are particularly important to your care, I’d also confirm participation directly with the provider’s office before making a final decision. I have seen this more times than I can count: a provider shows as in-network for a particular plan, a client goes to that provider, and the provider says they are not taking the plan and haven’t taken that plan in more than a year.
The cheapest Medicare plan can become surprisingly expensive if the care you want isn’t available where you expected it to be.
This Fall during the Annual Enrollment Period, don’t just check for the extras such as dental, vision, hearing, OTC, and grocery benefits. Check the doors the plan actually opens.
Missed the opening issue?
If you missed our previous discussion on the broader 2027 Medicare landscape, read Part 1 here to get the full picture behind this year’s enrollment period.
Information presented is believed to be current. It should not be viewed as personalized investment advice. All expressions of opinion reflect the judgment of the authors on the date of publication and may change in response to market conditions. You should consult with a professional advisor before implementing any strategies discussed. Different types of investments involve higher and lower levels of risk. There is no guarantee that a specific investment or strategy will be suitable or profitable for an investor’s portfolio. There are no assurances that a portfolio will match or exceed any particular benchmark.
Content should not be viewed as legal or tax advice. You should always consult an attorney or tax professional regarding your specific legal or tax situation. Estate planning is done in conjunction with your estate planning attorney, tax attorney, and/or CPA. Fusion Investment Advisors is not engaged in the practice of law or accounting.
Whether you’re turning 65, reviewing annual plan changes, or helping a loved one choose coverage, we can help you find a plan that fits your healthcare needs and budget.
Schedule a Medicare Consultation
