Medicare Help in Franklin, Spring Hill, and Middle Tennessee

Medicare Help in Franklin, TN, Before Your Plan Changes

Plans are changing for 2027 and some are ending altogether. Book a plan review with an independent local advisor and walk away with a clear plan to cover your doctors and prescriptions within your budget.

  • Independent advisor, not tied to one insurance company
  • Specialized guidance from a Registered Social Security Analyst®
  • Help all year, not just during enrollment

Book Your Medicare Plan Review

It takes about 30 seconds. No cost and no obligation, and Danny will reach out within one business day.

Medicare Shouldn’t Feel This Complicated

Every Fall the mail and the phone calls pile up. Plan changes, TV ads, and postcards promising the world. And this year, a lot of people are getting letters saying their Medicare Advantage plan won’t continue in 2027.

If that’s you, it’s easy to feel stuck and unsure what to do next. You don’t want to lose your doctors. You don’t want a surprise bill for a prescription you’ve taken for years. And you don’t want to spend your fall on hold with an 800 number.

You shouldn’t need a spreadsheet and a law degree to pick your health coverage. You need someone local who’ll look at your situation and explain your options in plain English.
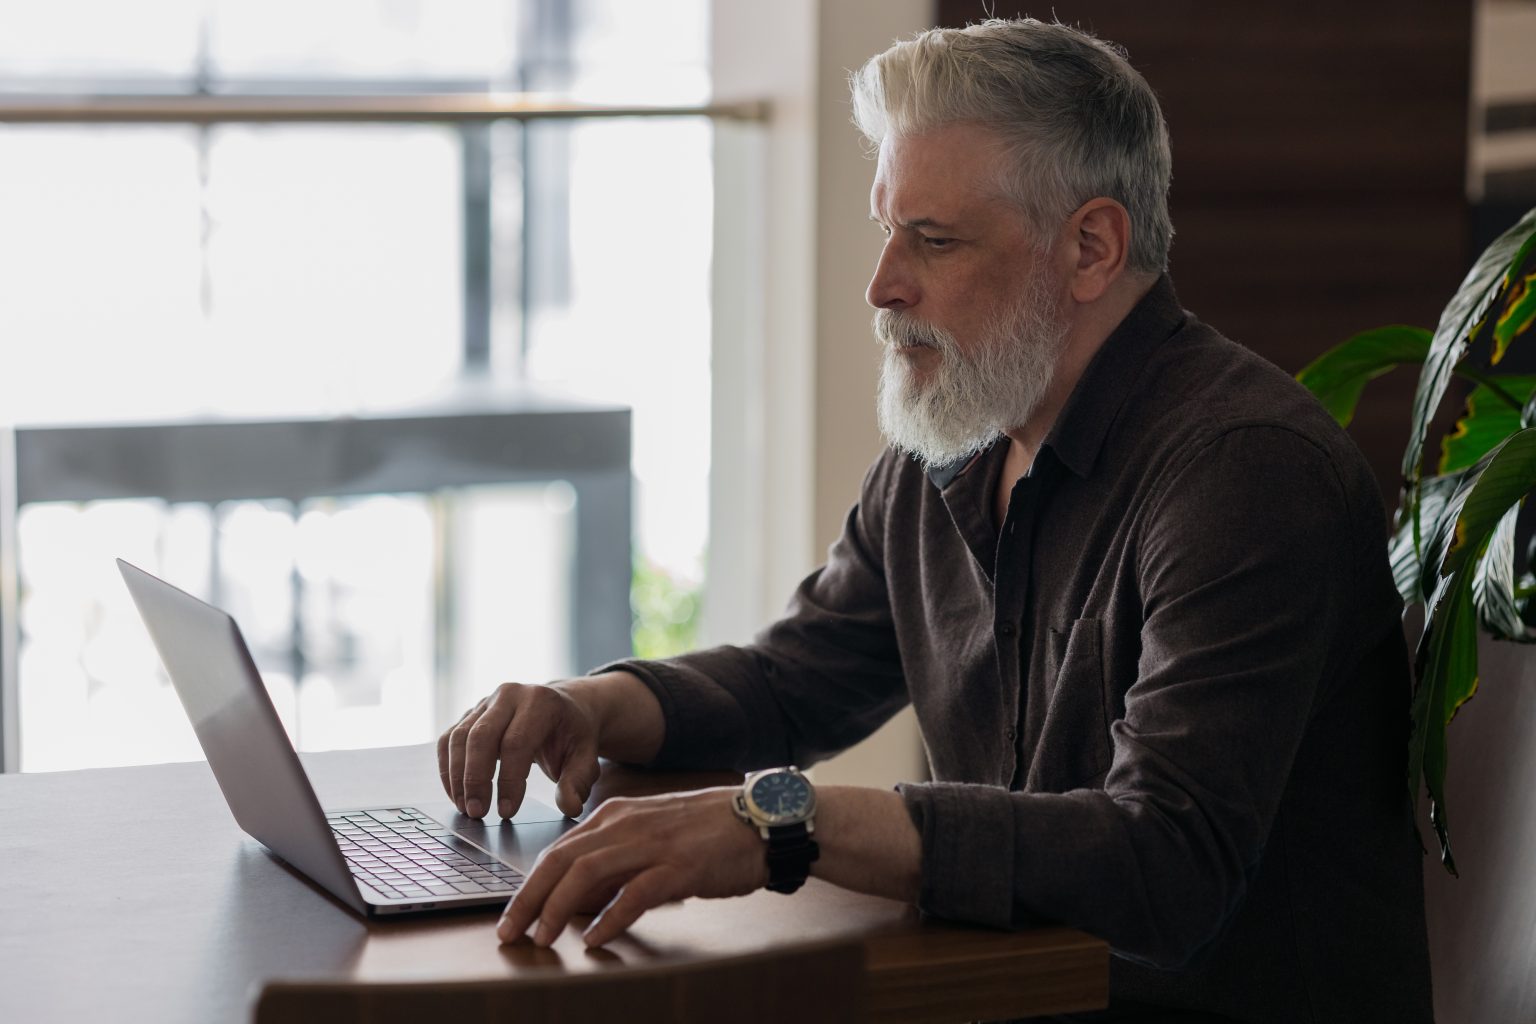
Retired man reviewing his Medicare plan options on a laptop at home
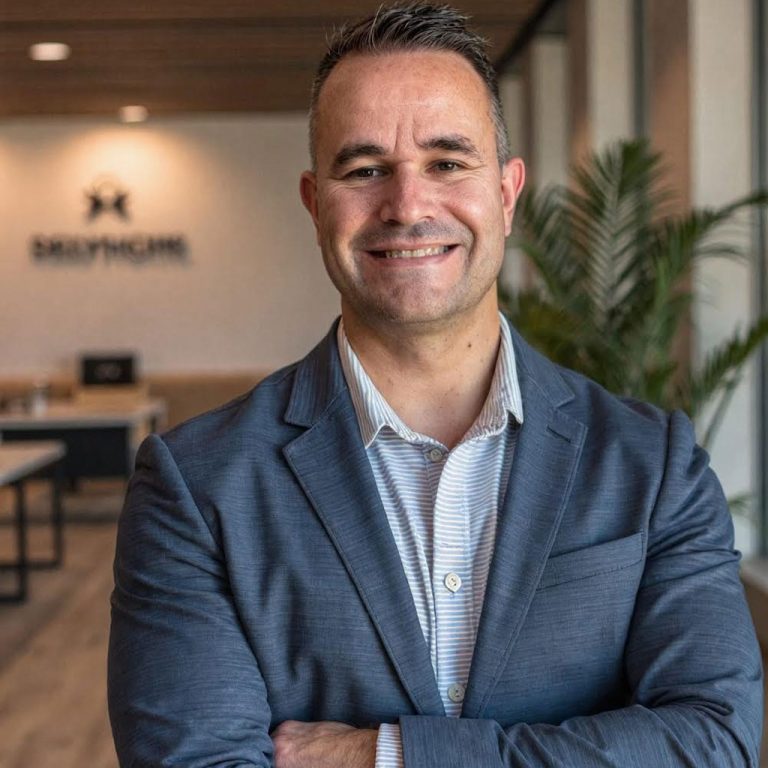
Danny Knelson, Medicare and retirement advisor in Spring Hill, TN

A Local Advisor Who Sees the Whole Picture

Hi, I’m Danny Knelson. I hear it from clients every fall. Medicare decisions feel stressful, and the stakes feel high. That’s because they are.

I’m an independent advisor based in Spring Hill, and I hold the Registered Social Security Analyst® designation. That matters more than it sounds. I know how your Medicare costs, your Social Security check, and your retirement income affect each other. Many agents only look at the plan. I look at how it fits with everything else.

Independent

I work with 10 insurance companies, so you see real options side by side.

Credentialed

Registered Social Security Analyst®, a designation few advisors hold.

Easy to reach

Reviews by phone or video, or in person within 30 miles of Spring Hill outside enrollment season.

Here all year

Questions about a bill in March get the same attention as enrollment questions in October.

If Your Medicare Advantage Plan Is Ending in 2027

A non-renewal letter means your plan is leaving your area or shutting down at the end of 2026. You didn’t do anything wrong. You do need to act, though.

Here’s what to know
1

You can choose a new Medicare Advantage plan during Annual Enrollment, October 15 to December 7.

Your new coverage starts January 1.
2

If you miss that window, you still have time.

The Medicare Advantage Open Enrollment Period runs from January 1 to the end of March 2027.
3

You have a guaranteed right to buy a Medicare Supplement without health questions.

When your Advantage plan ends, insurance companies can’t turn you down or charge you more because of your health. I’ve helped clients use this right before. The window is limited, so don’t sit on it.
4

If you do nothing, you’ll move to Original Medicare on January 1.

That can leave you without drug coverage, and going without it can mean a late penalty down the road.

The easiest next step is to bring your letter to a plan review. We’ll sort out your options together.

What the Wrong Medicare Choice Can Cost You

A plan that looks fine on a postcard can cause real problems later:

Your doctor or hospital isn’t in the new plan’s network

A prescription you rely on moves to a higher cost tier

A late enrollment penalty that stays with you for as long as you have Medicare

An IRMAA surcharge on your premiums you didn’t see coming

A missed deadline that leaves you waiting a year to fix it

A review before you enroll is the simplest way to catch these early.

Your Medicare Plan Review in 3 Simple Steps

1

Book your review.

Fill out the form or call (931) 382-2766. Pick a time that works for you.
2

Bring your list.

Your doctors, your prescriptions, your current plan card, and any letters from your plan.
3

Get a clear recommendation.

We compare your options side by side, and you decide. If a new plan makes sense, I’ll handle the enrollment paperwork. If your current plan is still the best fit, I’ll tell you that too.

Medicare Help for Every Stage

Turning 65

Your Initial Enrollment Period lasts seven months. It starts three months before the month you turn 65 and ends three months after the month you turn 65. Signing up late for Part B can mean a penalty that lasts for life, so it pays to plan a few months ahead.

Working Past 65

If you have health coverage through your own or your spouse’s current employer with 20 or more employees, you can usually delay Part B without a penalty. If you contribute to a Health Savings Account, plan your last contribution carefully. When you sign up for Part A after 65, your coverage can start up to six months early. HSA contributions made during those months can count as excess contributions, and the IRS charges a penalty on those. The safest move is to stop contributing six months before you enroll.

Retiring or Leaving Employer Coverage

When employer coverage ends, you generally have eight months to sign up for Part B without a penalty. Drug coverage has a shorter window. If you have retiree coverage, we’ll review how it works with Medicare before you make any changes.

Your Annual Plan Review

Plans change their costs, networks, and drug lists every year. Your plan mails an Annual Notice of Change each fall. A quick yearly review makes sure your plan still fits.

Medicare Advantage vs. Medicare Supplement in Tennessee

Most people in Tennessee end up choosing between two paths. Here’s how they compare.

How it works

Medicare Advantage: A private plan that replaces Original Medicare, often with drug coverage built in.

Medicare Supplement (Medigap) plus Part D: Supplements Original Medicare to cover gaps, paired with a separate drug plan.

Doctors

Medicare Advantage: Usually a network (HMO or PPO).

Medicare Supplement (Medigap) plus Part D: Any provider in the U.S. that accepts Medicare.

Monthly premium

Medicare Advantage: Often low.

Medicare Supplement (Medigap) plus Part D: Higher.

Costs when you get care

Medicare Advantage: Copays and coinsurance, up to a yearly out-of-pocket maximum.

Medicare Supplement (Medigap) plus Part D: Low and predictable, depending on the plan.

Travel

Medicare Advantage: Limited coverage outside the network.

Medicare Supplement (Medigap) plus Part D: Coverage across the U.S.

Switching later

Medicare Advantage: You can change plans every year during Annual Enrollment.

Medicare Supplement (Medigap) plus Part D: Switching into a Supplement later usually means answering health questions.

Neither option is right for everyone. The best fit depends on your doctors, your prescriptions, how often you travel, and what you’d rather pay monthly versus what you pay when you need care.

A note on drug plans

I help with Medicare Advantage and Medicare Supplements. I don’t enroll stand-alone Part D drug plans, but I’ll show you how to compare them on Medicare.gov so you don’t go without coverage.

How Medicare Connects to Your Social Security and Taxes

This is where most Medicare conversations stop short. Your Medicare decisions and your retirement income affect each other.

Your Part B premium usually comes straight out of your Social Security check.

A higher premium means a smaller deposit.

IRMAA can raise your premiums.

Medicare looks at your income from two years ago. A Roth conversion, a home sale, or a large IRA withdrawal can push your premiums up for a year. If your income dropped because you retired or had another qualifying life change, you can appeal to Social Security to lower it.

You don’t have to claim Social Security to get Medicare.

If you delay Social Security past 65, you’ll pay your Medicare premiums directly, either with a quarterly bill or by automatic monthly draft through Medicare Easy Pay.

As a Registered Social Security Analyst®, I build these pieces into the same conversation, so your Medicare choice and your income plan work together.

What It Feels Like to Have Medicare Handled

  • You know what you’ll pay and why
  • Your doctors and prescriptions are checked before you enroll
  • You have one local person to call when something goes wrong
  • You get a check-in every fall, so changes don’t catch you off guard
Family sharing a relaxed meal together outdoors

Key Medicare Dates to Know

Initial Enrollment

When: 3 months before your 65th birthday month through 3 months after

What you can do: Sign up for Medicare for the first time

Annual Enrollment

When: October 15 to December 7

What you can do: Join, switch, or drop a Medicare Advantage or Part D plan. Changes start January 1.

Medicare Advantage Open Enrollment

When: January 1 to March 31

What you can do: If you’re in Medicare Advantage, switch once to another Advantage plan or to Original Medicare

General Enrollment

When: January 1 to March 31

What you can do: Sign up for Part A or Part B if you missed your first window

Special Enrollment

When: Varies

What you can do: Change coverage after events like moving, losing coverage, or your plan ending

Medicare Questions We Hear Most

No. There’s no fee for a Medicare plan review. Insurance companies pay agents when a client enrolls, and your plan costs the same whether you use an agent or not.

A captive agent works for one insurance company and can only offer that company’s plans. An independent agent can compare plans from several companies and show you how they stack up.

You’ll move to Original Medicare on January 1. That may leave you without drug coverage or extra benefits you’re used to. You also have a guaranteed right to buy a Medicare Supplement for a limited time. It’s better to choose your next step before your current plan ends.

Often, yes. If you have health coverage through your own or your spouse’s current employer with 20 or more employees, you can usually delay Part B without a penalty. Your drug coverage also needs to be “creditable,” meaning at least as good as Medicare’s, to avoid a Part D penalty later. The rules change for smaller employers, so it’s worth checking before you turn 65.

IRMAA is a surcharge on Part B and Part D premiums for people with higher incomes. It’s based on your tax return from two years ago. If your income has dropped since then because of retirement or another qualifying life change, you may be able to appeal it.

No. You can enroll in Medicare at 65 and delay Social Security. If you’re already collecting Social Security when you turn 65, you’ll be enrolled in Parts A and B automatically. Your Medicare card usually arrives about three months before your coverage starts.

I don’t enroll stand-alone Part D plans. I’ll explain how drug coverage fits with your other choices and show you how to compare Part D plans on Medicare.gov.

Your Medicare card, your current plan card, a list of your doctors, a list of your prescriptions with doses, and any letters from your plan.

Yes. I’m licensed in Tennessee, Alabama, Florida, Georgia, Indiana, Kentucky, North Carolina, Ohio, and South Carolina. Most reviews happen by phone or video, so where you live doesn’t slow anything down.

Don’t Wait Until the Last Week of Enrollment

My calendar gets tight as December 7 gets closer. Book your review now and get your Medicare sorted before the rush.

Subscribe to our newsletter
The latest news, articles, and resources, sent to your inbox weekly.
By subscribing, you'll get Danny's weekly newsletter and related emails from Knelson Advisory Solutions. Unsubscribe anytime. See our Privacy Policy.
Copyright 2026 © Knelson Advisory Solutions, All Rights Reserved
Designed by MRB Media, Inc.
Investment advisory services are offered through Fusion Capital Management, an SEC registered investment advisor. The firm only transacts business in states where it is properly registered or is excluded or exempted from registration requirements. SEC registration is not an endorsement of the firm by the commission and does not mean that the advisor has attained a specific level of skill or ability. All investment strategies have the potential for profit or loss. Insurance products offered through Knelson Wealth Protection, LLC. Fusion Capital Management and Knelson Wealth Protection are affiliated entities.
We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.
Not connected with or endorsed by the United States government or the federal Medicare program.
Compensation received by licensed insurance agents for the sale of fixed annuities and other insurance products are separate and distinct from fees charged for advisory services. Insurance products also contain additional fees and expenses.
All insurance and investment strategies have the potential for profit or loss. Always consult with a licensed insurance professional who is qualified to evaluate your specific circumstances and to offer a professional opinion with respect thereto.
Annuity guarantees are subject to the claims-paying ability of the issuing insurance company. If you withdraw money from or surrender your contract within a certain period of time after investing, the insurance company may assess a surrender charge. Withdrawals may be subject to tax penalties and income taxes.
Social Security rules and regulations are subject to change at any time. Always consult with your local Social Security office before acting upon any information provided herein.
Content should not be viewed as legal or tax advice. You should always consult an attorney or tax professional regarding your specific legal or tax situation. Estate planning is done in conjunction with your estate planning attorney, tax attorney, and/or CPA. Fusion Investment Advisors is not engaged in the practice of law or accounting.